Why the world’s great powers are queuing up in Brazil’s mining country, and why Brasília refuses to pick a side
Nobody will fight a medieval tournament over Brazil’s minerals, but the contest is real. The weapons are financing packages, acquisitions and export controls. The prize is hard to picture: a grey metal in the steel of your pipelines and jet engines, and a handful of obscure elements without which no wind turbine, electric car or guided missile works.
The metal nobody has heard of
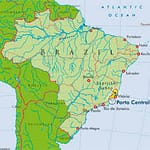
Start with niobium. Its main job is to make steel stronger and lighter, which matters in pipelines, bridges and aerospace alloys. Brazil holds over 90% of global reserves and production, and the supply is concentrated even within Brazil. Only three niobium mines operate worldwide, two in Brazil and one in Canada. The United States, for its part, has been 100 percent net import reliant on niobium, buying it from Brazil and Canada.
Here is where the rivalry shows up. Beijing does not need to own Brazil’s mines to hold leverage over them. A Chinese state-controlled entity owns the Catalão niobium mine, and a Chinese consortium holds 15% of the Araxá mine, which accounts for more than 80% of global niobium production. China is also a major buyer: it accounts for roughly 30% to 60% of global niobium consumption. A metal Washington cannot mine at home comes mostly from one Brazilian valley, partly with Chinese capital.
The rare-earth scramble
The louder fight is over rare earths, the 17 elements behind high-performance magnets. China refines the great majority of them, and its export restrictions in the last two years showed the rest of the world how exposed that leaves it.
Brazil is the obvious alternative. It claims the world’s second-biggest rare-earth reserves after China, including the heavy rare earths at the center of the US-China trade war. Its deposits sit in ionic clay, which is more concentrated and cheaper to produce than the hard-rock ores found elsewhere. Yet the country produces and refines less than 1% of the world’s rare earths, according to the International Energy Agency.
Washington is trying to change that. Serra Verde, then Brazil’s only rare-earth producer, secured a US$565 million financing package from the U.S. government in February. In April, US-based USA Rare Earth agreed to acquire it in a deal valued at $2.8 billion. That would move its output from Chinese refiners to American ones. At a São Paulo forum in March, US officials said they were interested in at least 50 critical minerals projects in Brazil worth billions of dollars.
China has not retreated. In 2024, state-owned China Nonferrous Metal Mining bought Taboca, an Amazon miner that produces tin and holds reserves of niobium, tantalum and hafnium. Chinese acquisitions in Brazil also include nickel mines valued at $500 million in 2025, plus stakes in tin, copper and lithium operations. And Brazil’s rare-earth exports to China boomed in 2025.
And Moscow?
Russia is the weakest player in this particular tournament, and I found no evidence of a major Russian stake in Brazilian niobium or rare earths. Its leverage over Brazil comes through BRICS and its own large mineral sector, not through ownership of Brazilian ground. Anyone picturing the three rivals of Washington as a unified team should note that China is by far the dominant player and that the combination exists mainly in cartoons.
Brazil’s reply: nobody gets the ore for free
What the cartoon cannot capture is that Brazil is not a spectator. The EU, South Korea, Japan, India, Canada and Australia have all pitched deals to Brasília, and Brazilian officials have a stated principle: Brazil’s historical policy is to “be friends with all countries from every bloc”, taking no side between the US and China.
The sticking point is value. Brazil has long exported concentrates and imported finished technology. Lula has resisted agreements that don’t guarantee processing and refining capacity inside Brazil. On September 16 he signed a National Policy on Critical and Strategic Minerals, with domestic processing and value-added work central to its goals.
Washington has also made its own task harder. When the US embassy held its critical minerals summit in São Paulo, no senior members of Lula’s administration attended. Washington went around the federal government, signing a preliminary agreement with Goiás, whose governor, Ronaldo Caiado, is a political opponent of Lula. Brazilian officials were privately annoyed. The federal talks have stayed difficult: Trump administration proposals were considered too generic by Brazilian officials.
The election that tilted the board
The minerals question became a campaign issue. Lula’s rival, Flávio Bolsonaro, called for stronger ties with Washington, including long-term cooperation over Brazil’s rare earths. Lula warned the US not to interfere and said Brazil would “never fit into anyone’s backyard”.
Lula won the October 25 runoff, giving him a fourth non-consecutive term that begins on 5 January 2027, though Bolsonaro has not conceded. For Washington, that means negotiating with a counterpart who wants refineries, jobs and technology transfer on Brazilian soil, and who has little interest in becoming a raw-material depot for anyone.
The real contest
The winner will not be the power that arrives with the biggest check. It will be the one that can offer Brazil what it actually wants: processing plants, magnet factories and a share of the value chain, in return for a stable, long-term supply. China has the incumbent advantage in refining and the buyers. The United States has capital, urgency and a fast-growing list of deals. Brazil holds the ore, a new law and, for now, the choice.
That is a stronger position than any knight in a tournament has ever had. The jousting will continue, but this time the horse owns the field.