

Why Brazil is quietly becoming the Netherlands’ most interesting new business address

eyesonbrasil
Amsterdam, August 17, 2026 – Dutch investors have never really left Brazil. The Netherlands is already the single largest immediate European investor in the country, holding a bigger share of Europe’s Brazilian FDI stock than Luxembourg and Spain combined. What’s changed in 2026 is the case for going further: a landmark EU-Mercosur trade deal is now provisionally in force, Brazil’s tax rules for foreign investors have been modernized, and a startup ecosystem that spent the early 2020s overheating has matured into something far more investable. For Dutch companies and founders who have watched Brazil from a distance, the distance just got a lot shorter.
The trade deal that changes the math
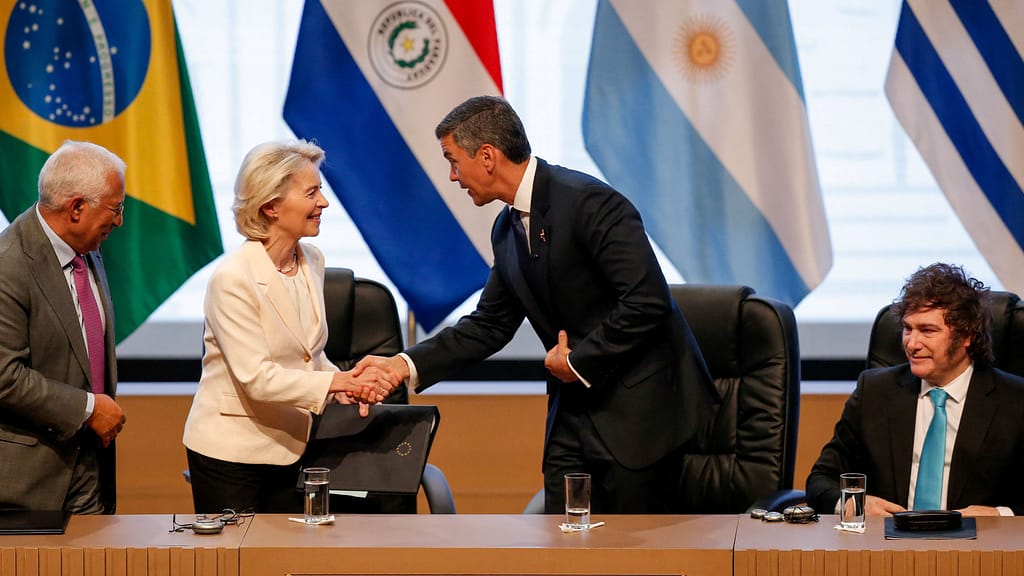
After more than 25 years of on-and-off negotiation, the EU-Mercosur agreement stopped being a talking point and became operational. The Interim Trade Agreement — the tariff-cutting, market-access core of the deal — has been provisionally applied since May 2026, creating one of the largest free trade zones in the world, spanning roughly 720 million consumers across the EU and the Mercosur bloc of Argentina, Brazil, Paraguay, and Uruguay. The fuller Partnership Agreement still has to work through ratification in all 27 EU member states, and a European Parliament referral to the Court of Justice has put that broader process on a slower track. But the trade pillar that actually matters to a Dutch exporter or investor — reduced tariffs, new government procurement access, a more predictable regulatory framework — is already live.
For Dutch companies already active in Brazil, that’s not an abstract diplomatic win. It’s a concrete opening: Mercosur countries agreeing to open their public procurement markets to EU firms, tariff reductions across agriculture, automotive, pharmaceuticals, and chemicals, and a more stable legal footing for the kind of long-horizon investment that Brazil has historically made nerve-wracking.
Yes, there’s a new tax — and it’s actually good news for predictability
For almost thirty years, one of Brazil’s quieter advantages for foreign investors was that dividends sent home were not taxed at source. That ended on January 1, 2026. Under Law 15.270/2025, Brazil now applies a 10% withholding tax on dividend payments to foreign shareholders above BRL 50,000 a month — roughly €8,565 today. It’s a real change, and it means a Brazilian subsidiary sending profits back to Amsterdam or Rotterdam now keeps a slice in Brazil rather than repatriating it in full.
But read the change in context: it brings Brazil in line with how most of the world already taxes outbound dividends, as part of a broader tax modernization that will be phased in gradually through 2033. For investors who prize predictability over the specifics of any single rate, a country converging toward global norms — rather than one where the rules could swing unpredictably — is, on balance, a more investable one.
Where Dutch expertise has a natural home
Three sectors stand out as places where what the Netherlands is genuinely good at lines up with what Brazil actually needs right now.
Agri-food technology. This is the most obvious fit, and Brazilian producers know it. Brazil is an agricultural superpower; the Netherlands is the world’s second-largest agricultural exporter despite being smaller than several Brazilian states, built almost entirely on precision farming, seed technology, greenhouse engineering, and water management. Brazilian producers are increasingly under pressure to meet European sustainability and food-safety standards to keep exporting into the EU — precisely the standards Dutch agtech was built around. Climate adaptation tools, precision irrigation, and cold-chain logistics for perishables are all areas where a relatively small Dutch company can plug directly into Brazil’s enormous agricultural base.
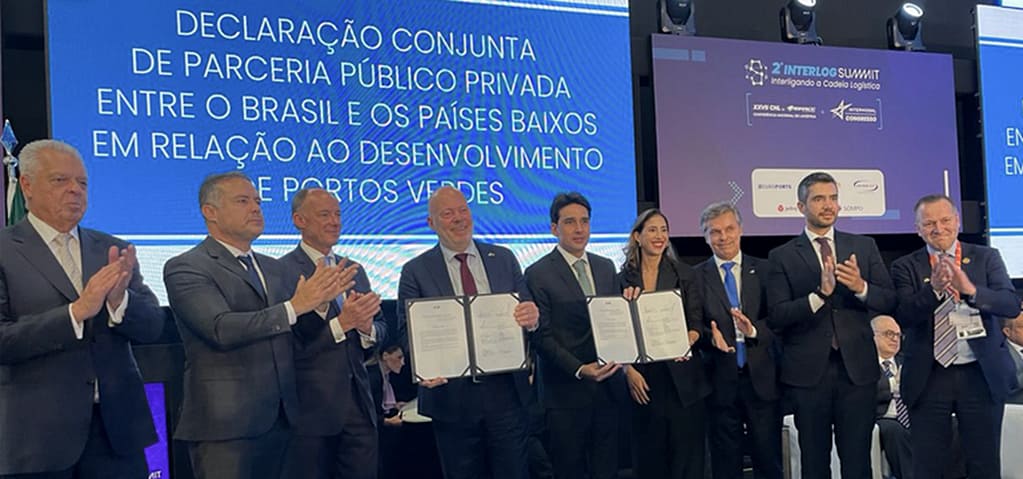
Logistics and supply chain infrastructure. The Netherlands built its economy on being Europe’s logistics gateway, and Brazil badly needs that expertise applied to its own ports, cold chains, and multimodal freight networks. With Rotterdam-honed know-how in supply chain optimization and integrated logistics, Dutch firms are well placed to help Brazil solve a problem that has quietly capped its export competitiveness for years: getting goods from a farm in Mato Grosso to a ship in Santos efficiently.
Sustainability compliance and green energy. Brazil already generates about 88% of its electricity from renewable sources — one of the cleanest large power grids on Earth — and it’s still investing aggressively to expand that lead. More than $15 billion has been earmarked for offshore wind and green hydrogen projects alone, and the domestic renewable energy market, valued at roughly $17.4 billion in 2025, is projected to nearly double to $31 billion by 2034. Dutch expertise in offshore wind engineering, water management, and sustainability certification — refined over decades of North Sea projects and EU compliance regimes — has an obvious export market here.
A startup scene that grew up
Brazil’s startup ecosystem in 2026 is not the one international investors remember from its 2021 boom, when the country pulled in a record $9.4 billion in venture capital largely on pandemic-era momentum and growth-at-any-cost logic. What exists now is calmer, larger, and considerably more disciplined — arguably a healthier place to actually put money to work.

The numbers tell the story of scale: somewhere between 20,000 and 57,000 active startups depending on how you count, roughly 25 unicorns, and still comfortably the largest venture-funded market in Latin America. Brazil’s central bank has held the Selic rate at 14.5% through 2026, which has done exactly what high rates are supposed to do — forced capital to become selective rather than disappearing. Early-2026 institutional funding rounds totaled around $424 million across roughly 50 deals, smaller in count than the boom years but built on companies with real unit economics rather than pure growth stories.
Four verticals are where the serious capital and the serious opportunity now overlap:
- Fintech remains the backbone of Brazilian tech, and for good reason. Pix, the central bank’s instant payment system, and Open Finance regulations have built a financial infrastructure layer that didn’t exist five years ago — one that rewards startups building on top of it in payments, credit, fraud detection, and reconciliation rather than trying to replace it. Nubank alone now serves over 100 million customers across Brazil, Mexico, and Colombia, evidence of how large a well-built fintech platform can scale from a Brazilian base.
- Agtech, tied increasingly to Brazil’s new carbon market under Law 15.042, sits at the exact intersection of Brazil’s agricultural scale and the sustainability credentials Dutch investors already understand.
- AI and enterprise software, now cutting across every other vertical rather than standing apart from them.
- Green and climate tech, riding the same renewable energy expansion driving the broader infrastructure story.
São Paulo remains the center of gravity — home to something like 60% of Brazilian startups and the vast majority of its unicorns, backed by accelerators like Cubo Itaú and Distrito and a deep university talent pipeline from USP and Unicamp. But founders and investors willing to look past Faria Lima are finding real depth in Belo Horizonte, where Google chose to open its first Latin American R&D center, and in regional hubs building strength in agritech, legaltech, and SME software that never depended on São Paulo in the first place.
The relationship already runs deep — this is where it gets wider
None of this is a cold start. Trade between the two countries already flows in both directions at real scale: Brazil exported roughly $11.75 billion to the Netherlands in 2025, led by fuels, iron and steel, meat, and coffee, while Dutch exports to Brazil — led by pharmaceuticals, machinery, and vehicles — reflect a Netherlands that already sells Brazil precisely the kind of advanced equipment and technology its economy is trying to scale up.
That existing relationship is also institutionalized in a way few bilateral business ties are. The Brazil Network Day, hosted by the Brazilian Embassy in The Hague and now in its latest edition at KPMG’s Amstelveen headquarters this November, draws several hundred executives, government officials, and heads of Brazilian multinationals already based in the Netherlands — a standing forum for exactly the kind of relationship-building that cross-border investment actually depends on.
The honest caveats
None of this makes Brazil a simple market. The EU-Mercosur agreement’s fuller Partnership Agreement still faces a genuinely uncertain ratification path through 27 EU parliaments and a pending opinion from the European Court of Justice — the trade pillar is live, but the broader legal architecture around it is still being built. Brazil’s new dividend tax, while predictable, is a real cost that needs modeling into any investment case. And Brazil’s regulatory and tax environment, even after genuine modernization, remains more complex than most Western European markets — this is a country where local partnerships and Portuguese-language capability aren’t optional extras but the actual price of entry.
But for Dutch businesses that have spent years exporting equipment and expertise to Brazil from a distance, and for Dutch investors who have already made the Netherlands the largest immediate European stakeholder in the Brazilian economy, 2026 is the year the case for moving closer got substantially stronger. The trade barriers are coming down, the startup market has stopped rewarding hype, and the sectors where Brazil most needs outside expertise — agri-food, logistics, sustainability, green energy — happen to be exactly where Dutch business has spent a century building its reputation.