Why Brazil’s Voluntary Carbon Market Is Turning Heads Abroad
eyesonbrasil
Amsterdam, August 12, 2026 – Picture a stretch of Amazon rainforest the size of a small European country, standing because someone, somewhere, paid to keep it that way. That’s the quiet transaction at the heart of Brazil’s voluntary carbon market (VCM) — and it’s quickly becoming one of the more compelling stories in global climate finance.
For foreign investors scanning the world for credible, high-impact places to put sustainability capital to work, Brazil keeps landing near the top of the list. Here’s why.
An Almost Unfair Natural Advantage
Brazil isn’t just another player in the carbon credit game — it holds roughly 15% of the world’s voluntary carbon offset supply. That’s not a marketing number; it reflects the sheer scale of the country’s forests, wetlands, and agricultural land, all of which can be converted into verified emissions reductions or removals. Few countries on Earth can match that raw ecological capacity, and none can match it at Brazil’s price point.
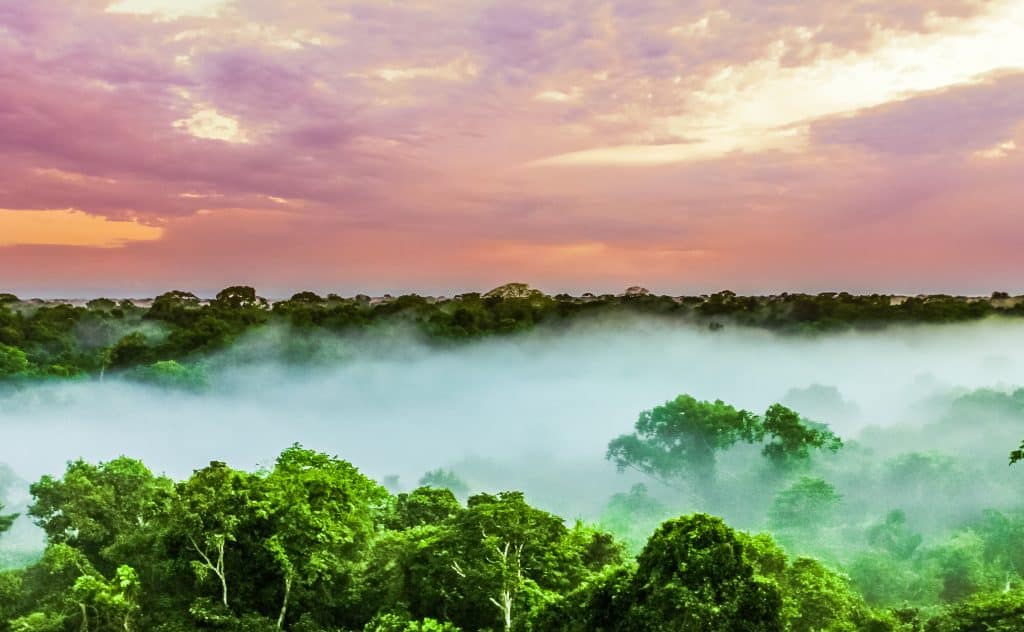
View on sunset over the trees in the Brazilian rainforest of Amazonas
Add to that the growing appetite among global corporations for high-quality, nature-based credits with genuine social co-benefits — projects that don’t just lock away carbon but also support indigenous communities and rural livelihoods — and Brazil’s forests start to look less like a liability to protect and more like an asset class in their own right.
Regulation Is Finally Catching Up
For years, skeptics pointed to regulatory uncertainty as the market’s Achilles’ heel. That’s changing fast. Law 15.042/2024 established Brazil’s national emissions trading system, the SBCE (Sistema Brasileiro de Comércio de Emissões), creating a formal legal architecture — modeled loosely on the EU’s ETS — that lets the regulated and voluntary markets coexist rather than compete.
Crucially for investors, this isn’t regulation for regulation’s sake. Companies emitting over 10,000 tCO2e per year will soon face mandatory reporting requirements, which is expected to create fresh domestic demand for verification services and offset credits. A national carbon credit registry, targeted for 2026, aims to add another layer of transparency, making it easier to trust — and trade — Brazilian-origin credits on the international stage.
In the meantime, certification through established international standards continues to give foreign investors a reliable entry point, offering assurance around credit authenticity and quality while the domestic system matures.
Money on the Table, Literally
Brazil isn’t waiting passively for the world to notice. At COP28, the government floated the Tropical Forests Forever fund — an ambitious plan to mobilize roughly $250 billion from sovereign wealth funds, private investors, and even the oil sector to pay for forest protection and restoration across some 80 tropical nations. At COP30, Brazil went further, proposing an “Open Coalition for Carbon Market Integration” to harmonize standards and link trading systems worldwide, aiming to boost liquidity and predictability for everyone involved.
These aren’t small gestures. They signal a government actively trying to make itself the most attractive address in the world for climate capital — and positioning its forests as core national infrastructure, not just scenery.
The Numbers Investors Actually Care About
Strip away the diplomacy and the growth story is striking on its own. Brazil’s carbon credits market is projected to grow at a compound annual rate of over 28% between 2026 and 2034, eventually reaching an estimated $25.2 billion in value. That kind of trajectory is rare in any asset class, let alone one tied directly to environmental outcomes.
Foreign capital already plays an outsized role on the demand side: international buyers account for the majority of demand for Brazilian-origin credits in the voluntary market, drawn by the scale, credibility, and biodiversity value that Brazilian projects offer.
The growth trajectory for Brazil’s voluntary carbon credit market, based on Grand View Research estimates: from $62.2M in 2023 to a projected $486.7M by 2030 — a roughly 34% compound annual growth rate, driven largely by afforestation and reforestation credits, with energy efficiency projects growing fastest. Worth noting: this is the voluntary segment specifically. Brazil’s total carbon credits market (voluntary + compliance combined) is a much bigger number — projected to hit $25.2B by 2034 — since the new SBCE compliance system will dwarf voluntary volumes once it’s fully phased in.
Not Without Its Fine Print
None of this means foreign investors can simply show up and start signing checks. Brazil restricts foreign ownership of rural land, so most carbon project investments are structured through partnerships, leases, or corporate vehicles rather than direct land purchases. Tax treatment varies depending on how a deal is structured, and Brazil’s broader tax reform — replacing several legacy taxes with a new IBS/CBS system starting in 2026 — still leaves some open questions about how carbon credit transactions will ultimately be taxed.
The commercial backbone of most deals, the Emission Reduction Purchase Agreement (ERPA), typically locks in terms for 10 to 30 years. That’s a long horizon, which means getting the legal structure right at the outset — anticipating regulatory shifts, currency movements, and operational risk — matters enormously.
The Bigger Picture
Strip away the acronyms and the appeal is straightforward: Brazil offers scale, credibility, government momentum, and a market still early enough in its formal regulatory life to reward investors who move thoughtfully now. It’s not a risk-free market — few emerging frameworks are — but it’s one where the fundamentals (forest, finance, and political will) are unusually well aligned.
For foreign investors willing to navigate the legal nuances, Brazil isn’t just participating in the global carbon economy. Increasingly, it’s positioning itself to help write the rules for it.
This article is for general informational purposes and does not constitute investment, legal, or tax advice. Carbon market regulations in Brazil are evolving; investors should consult qualified local counsel before structuring any transaction.